

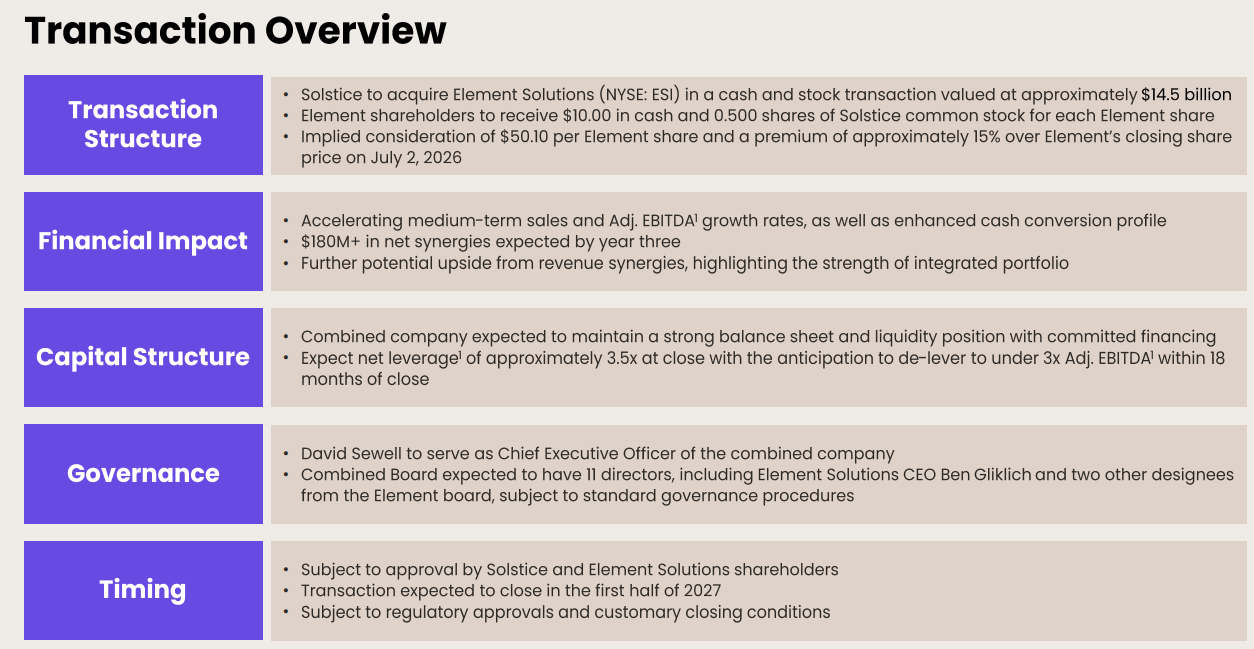
Early this week, Solstice (SOLS) announced that it was going to merge with Element Solutions (ESI) in a rough merger of equals to create an advanced packaging solutions juggernaut. Deal terms are ~$10 per share in cash as well as 0.5 shares for every ESI share.
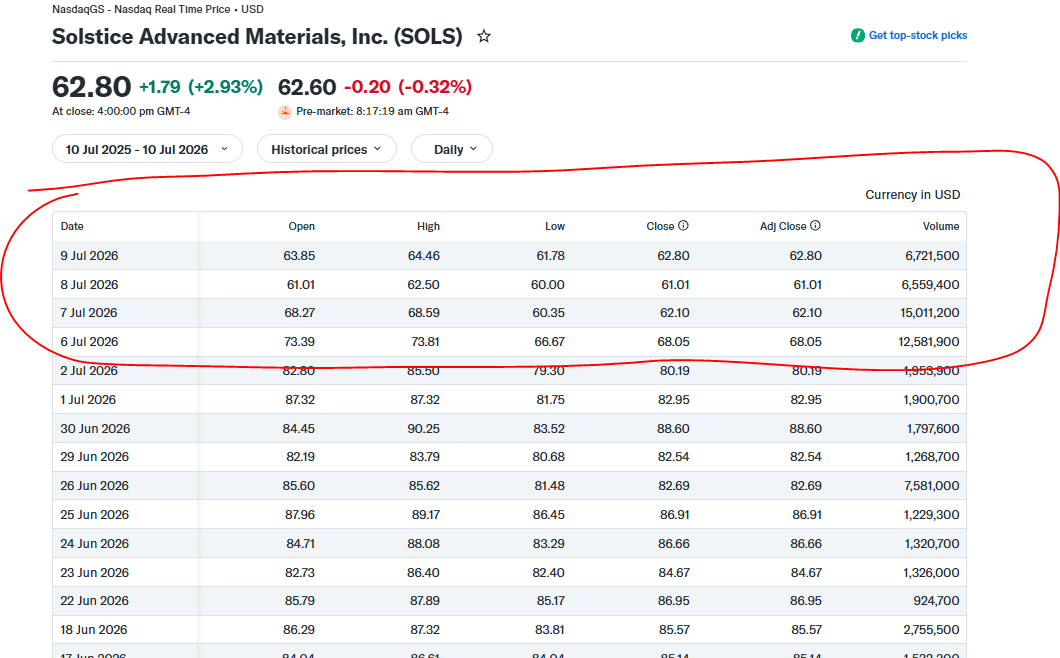
At first glance, I did not like this deal, and the market did not as well - shares had touched $90 a few weeks ago (up ~100% from our initiation), and traded down to $80 on a weak market for all semicon related names. On the back of this news break, shares collapsed and are now in the low 60s, give and take.
The stock has reset significantly now. Valuations have reset and the investment thesis is different. One could cry over spoiled milk or look at this entire thing with a fresh pair of eyes.
Prior to the acquisition, SOLS had three standout divisions - the largest was refrigerants where SOLS shared a duopoly with Chemours (CC), followed by the electronic materials division which is partially contributed by a dominant copper sputtering target business, and last but not least, the owner of the sole nuclear conversion site in the US. Whilst this was a nice hodge podge of assets, it was perhaps a little difficult for the market to price the entity - especially with refrigerant peer, CC, having a low multiple, or the fact that whilst nuclear was poised to grow significantly in the next few years, it was simply not in the financials yet. Moreover, the rest of financials were obscured by other non-semiconductor related, low multiple segments which also lacked growth (see image below).
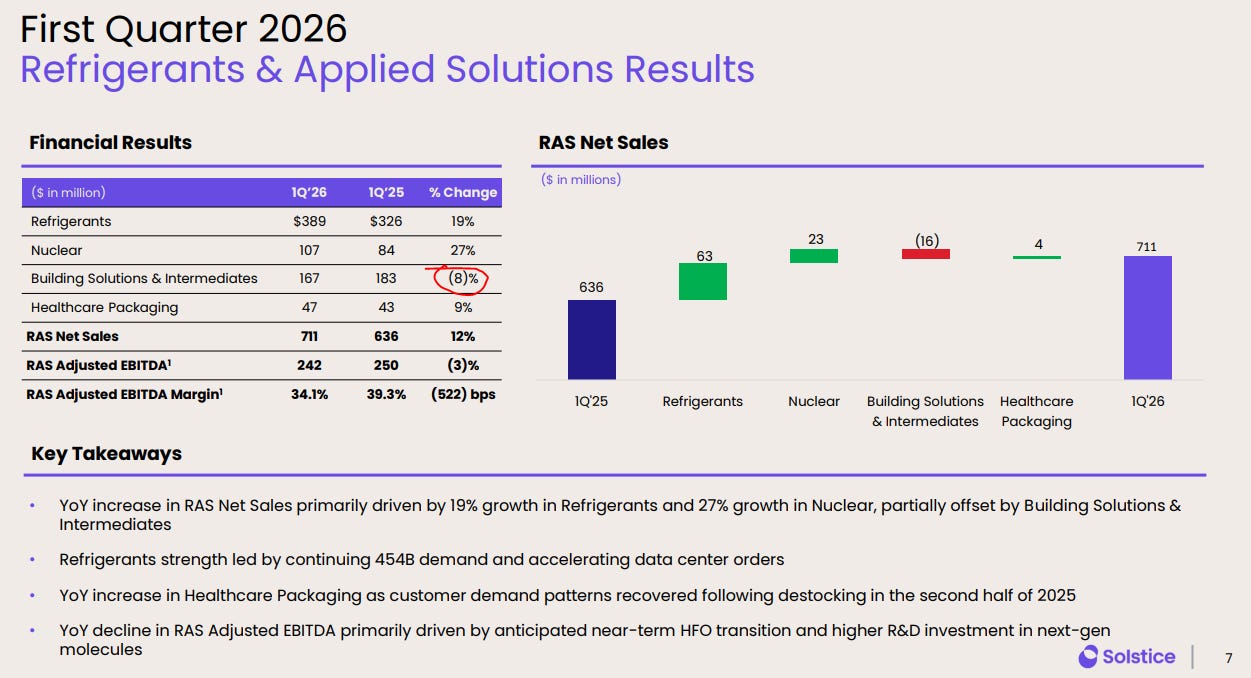
Fwiw, SOLS only guided to a 2-3% increase in revenue YoY for FY26. Along with cost issues plaguing EBITDA, SOLS Q1 earnings report was not greeted with the most fanfare.
CEO David Sewell is a hype chaser and he’s not shy to stich companies together. He had previously stitched up Smurfit WestRock. And being the hype chaser that he is - every past press release, from wanting to invest over $220m to expand its ballistic fiber manufacturing plant in Virginia to ride the defense wave, to expanding the Metropolis conversion site’s production capacity, as well as hosting a nuclear webinar which was greeted with a loud yawn - SOLS did feel like it was going neither here nor there for quite a bit.
Mr Sewell finally decided to stick to what he knows best - stitching companies together. As it is now abundantly obvious to us all, at least so far*, the clear theme going forward is AI and with chips layers consistently increasing across the entire chip catalogue, SOLS proposed acquisition of ESI will create a domestic advanced packaging juggernaut to capitalize on the said theme.
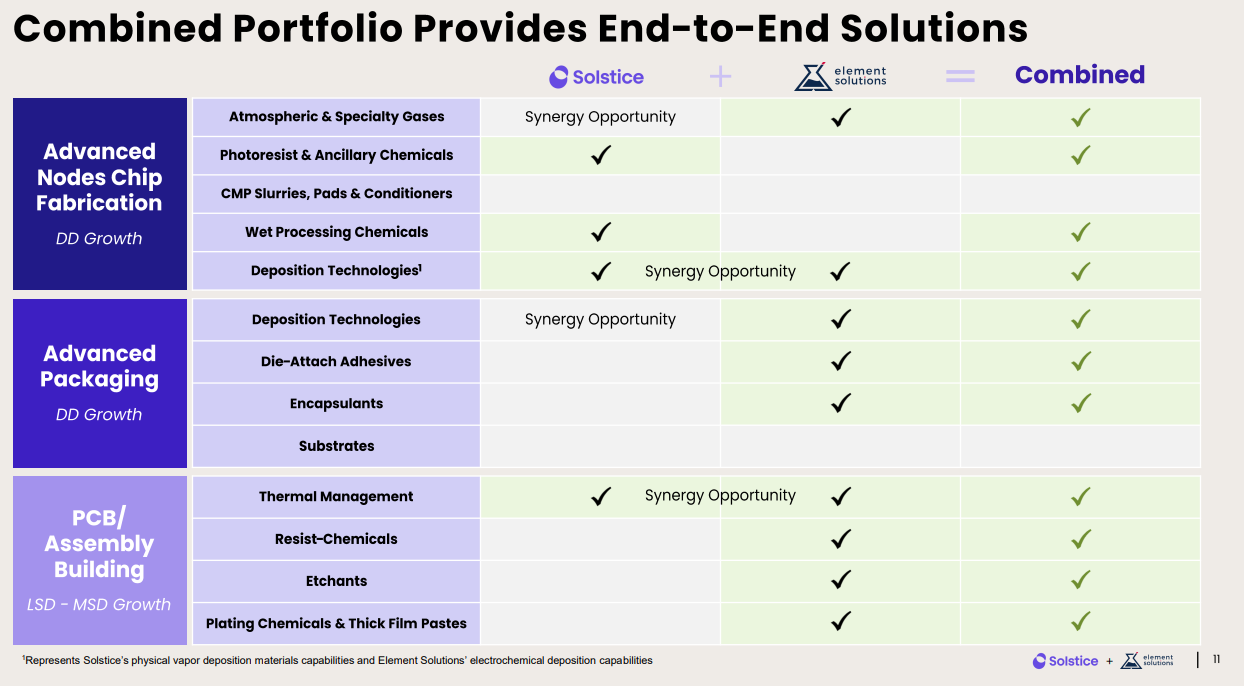
ESI, being a roll-up in itself, has its tentacles stretched across the semiconductor, advanced packaging and PCB materials space. Post merger with Solstice, the pf entity will have even deeper roots within the semiconductor space as that is what SOLS brings to the table mainly.
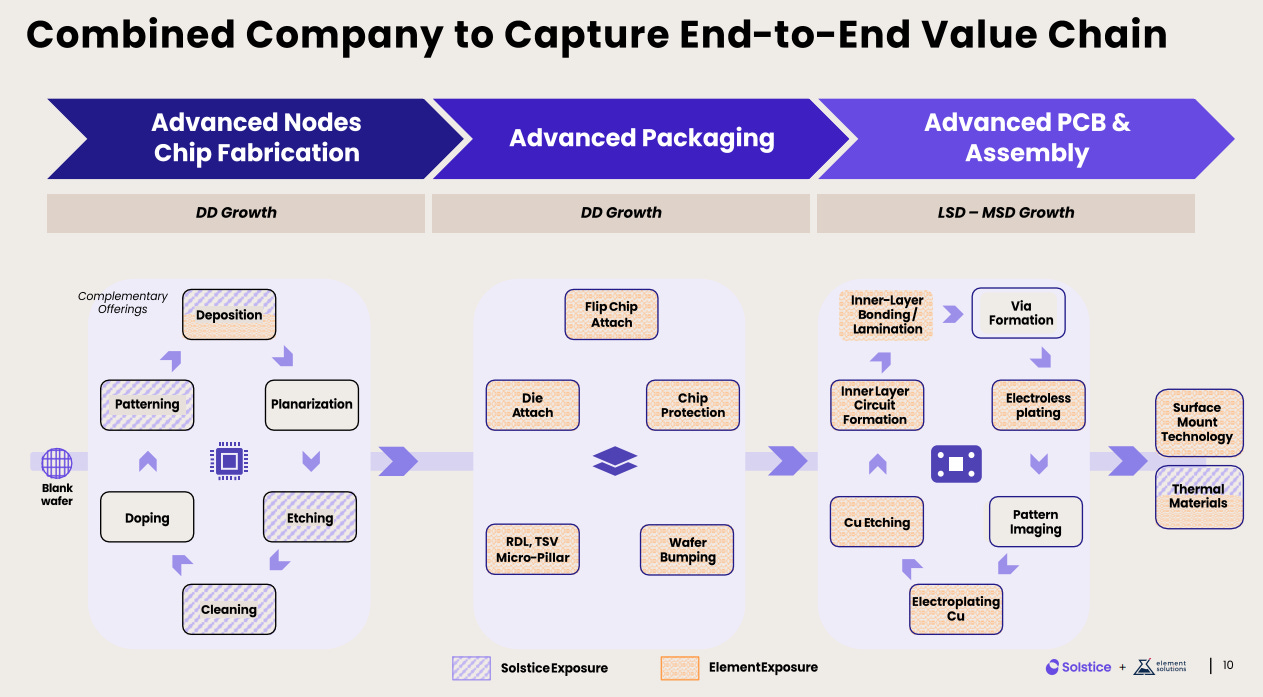
There will be a few overlaps that SOLS has quantified synergies from as well, which we shall see in abit.
With that, this juggernaut will almost become a domestic advanced packaging giant - the process by which multiple semiconductors (“chiplets”) e.g. two GPUs or say a GPU and HBM, are stitched together to form a single package, enabling the creation of super-powered chip-sets, without the need to constantly defy physical limitations i.e. make transistors smaller and smaller. With the demands of a post-AI world, advanced packaging has become a necessity and hence, the space is projected to grow in the high teens through 2030.
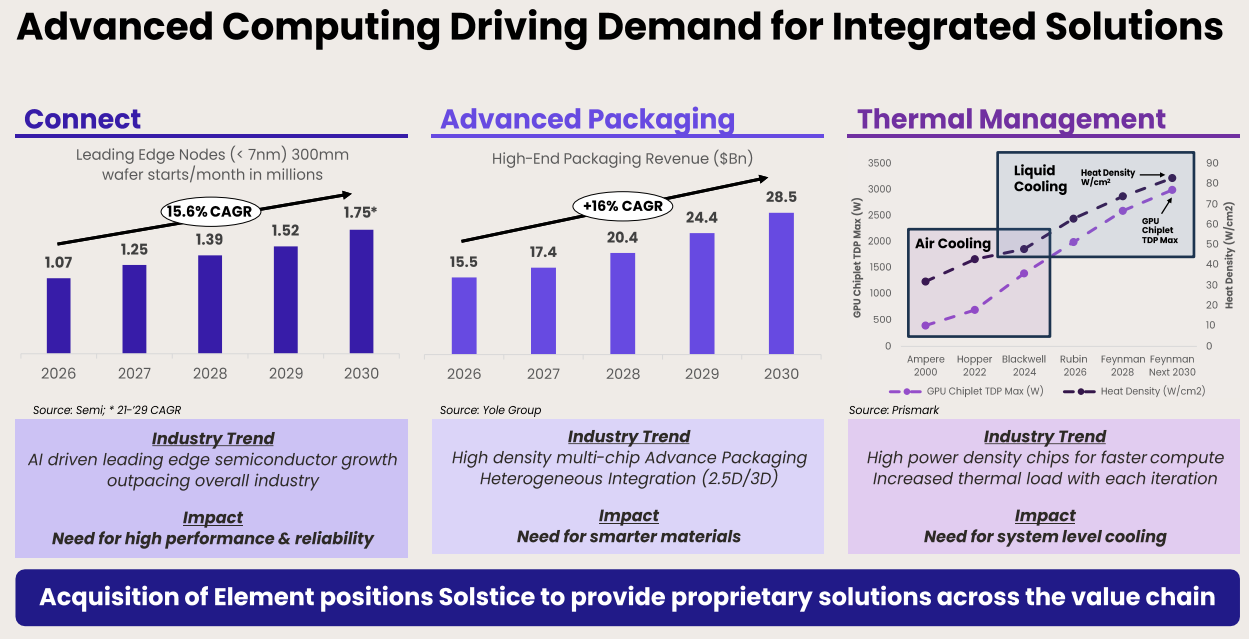
With that, we now have, and likely what David Sewell wanted, a proforma entity with higher exposure to semicap beta, and not just to the downside (as SOLS was prior).
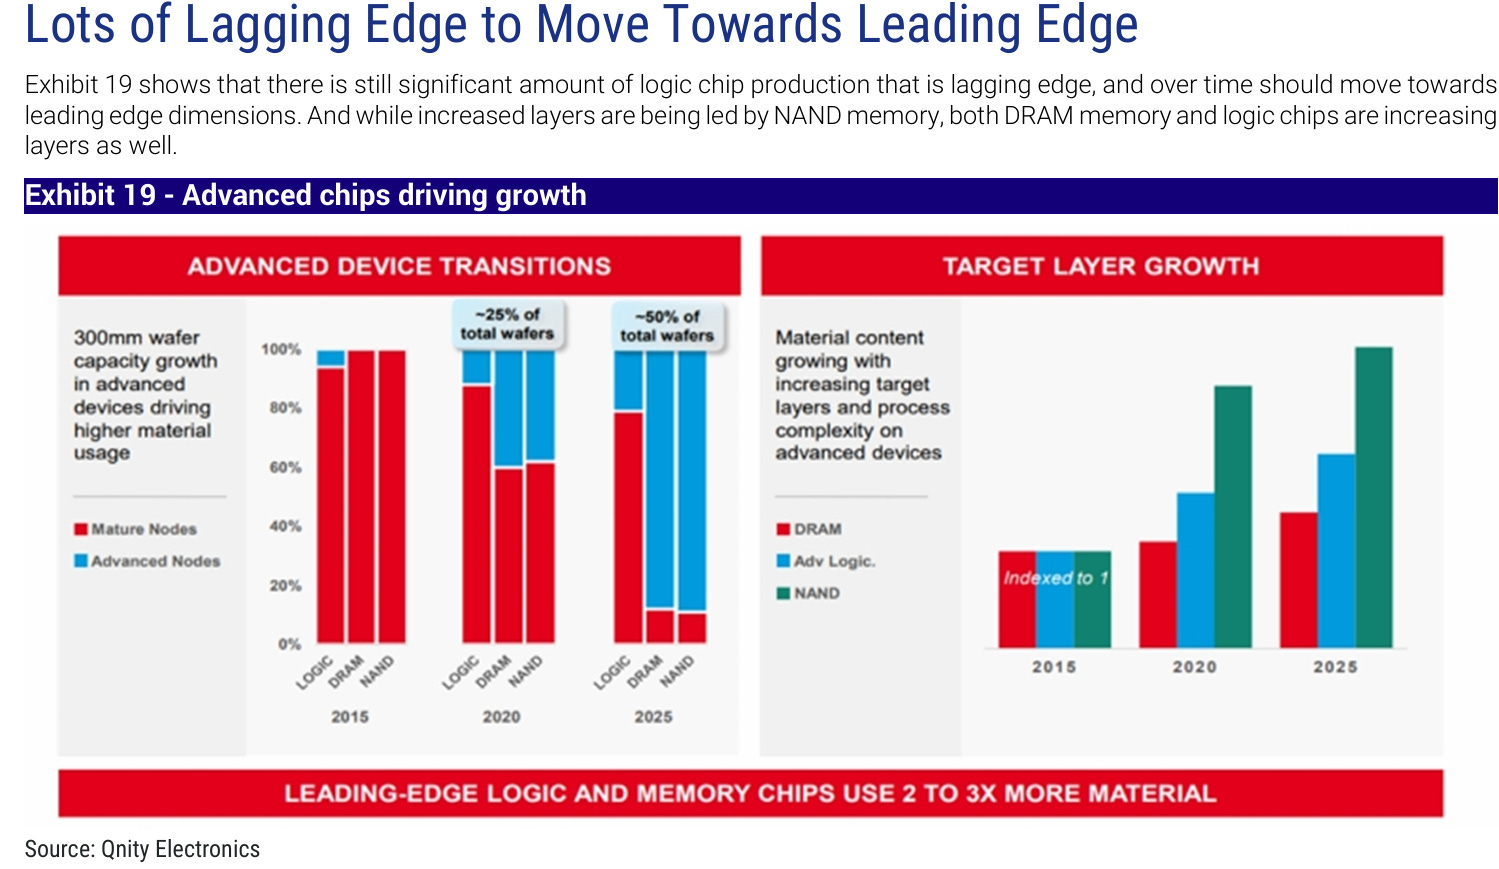
Hence, if the assumption that more advanced chips would be needed going forward holds, not only for current leading edge chips getting way more complex, but also the advancement of current mature nodes toward leading edge, then advanced packaging solutions become ever more important.
Why has the stock been dislocated so bad?
Shares have been dislocated likely due to a confluence of factors.
1) Legacy owners of the nuclear angle have sold down
Note, SOLS’ nuclear thesis became wide-spread on the back of Citrini’s report in Feburary this year. Now that nuclear has been diluted down to an even smaller sliver of the pf entity, it is likely many who were playing for that thesis, dumped shares.
I didn’t like it at the traded prices at the time of announcement either. How did I trade this? I managed to dump my entire position pre-market at exactly ~75/share because I suspected a puke into the open. I’m still sitting on a bunch of sold puts that are currently ITM and thus significantly red MTM.
This move down is also likely exaggerated by arbs shorting the SOLS stock to lock in the ESI spread.
Around ~41m shares have traded since the announcement, which is about ~25% of SOLS total shares outstanding.
2) Merger was initially struck at a high multiple
When the deal was initially announced, it was done at an implied US$14.5bn EV, which would equate to ~22x FY26 EV/EBITDA on ESI. At the current share price of SOLS, the takeover would be ~US$12.2bn due to the stock component, which would equate to around 18x FY26 EBITDA for ESI.
3) Potential integration risks
As with all mergers, there are potential integration risks when two giant entities combine.
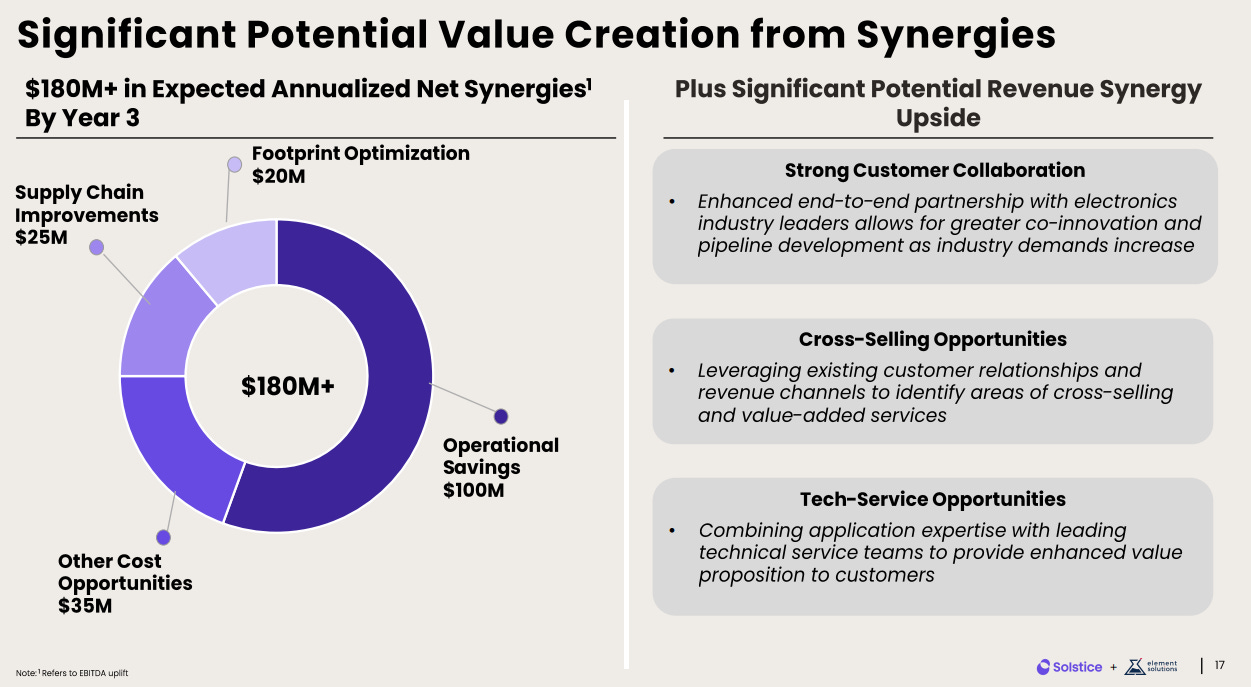
Management guided to an estimated ~US$180m of cost synergies which represent ~2.5-3% of the pf entity’s revenue. Not too audacious an estimate, and doesn’t include revenue synergy upside.
Where are we now?
As per management, the combined company will now be bigger, sport a higher EBITDA margin than both companies as standalones, with a much better growth profile and cash conversion rate.
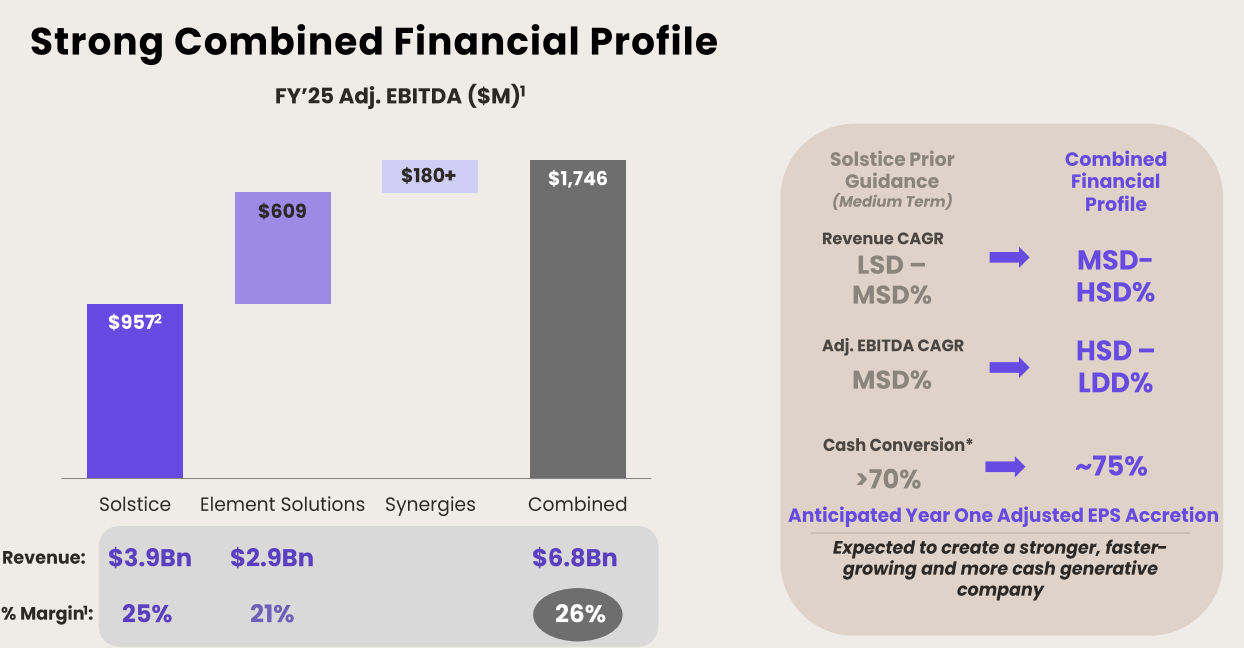
At ~62 per share, the new PF SOLS is trading at ~13.5x FY25 EBITDA, on the assumption of synergies and 3.5x net leverage.
Synergies will take time to be realized but it is worth noting that SOLS was guiding to ~1bn of EBITDA midpoint and Element was already guiding to ~675m EBITDA midpoint, both for FY26. That EBITDA growth for each standalone entity adds up to ~109m of EBITDA and would make up for ~60% of the forecasted synergies.
As mentioned, there may be other near term integration costs, but given that SOLS trades at such a wide spread relative to peers that a bet here seems favorable.
As seen in the table below, SOLS trades way below its closer electronic materials peers, both going for at least 20x EBITDA.
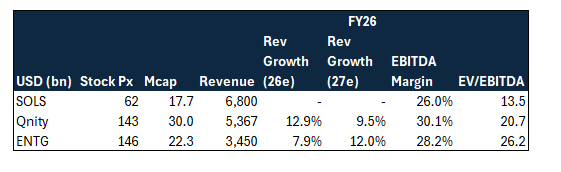
I don’t expect SOLS to trade at the same multiple as peers for various reasons:
1) Higher revenue growth and better EBITDA margins.
As the slide above shows, pf SOLS will have a revenue CAGR of MSD - HSD% so it likely grows slower than its aforementioned peers.
EBITDA margins of 26% after synergies are also nothing to write home about as peers are a league above, closing in on, or at, 30% margins.
2) The S&P 500 inclusion market cap threshold is at ~US$23bn mcap. Qnity was included last year and ENTG will likely be included soon as it pushes higher and eventually result in a new wave of passive buying.
Should SOLS push back into the high 70s and low 80s, its larger size would mean that it would be potentially included into the S&P 500 which could serve as a liquidity catalyst for additional rerating.
Nevertheless, even a slight discount at say 18x EBITDA, should yield a $95 stock price, implying a ~53% upside from here.
Anyway, that’s all from me at the moment. Sharpening a few other trades and will potentially write on them soon.
Ciao.