

The Korean stock market is a fascinating one. Recently resurrected from the dead, the KOSPI is up significantly YTD, despite the recent carnage. One might think the Korean market as a whole would have been well picked over but the strong ascent was entirely on the back of a booming memory stocks - SK Hynix (of which I was stopped out recently), and Samsung Electronics. Whilst many are trying to time the memory cycle - of which I have no unique opinion on - there remains a large swatch of Korean small-caps that are trading at discounted multiples - whereby should they have been listed in the US, would have perhaps garnered significantly higher multiples (?).
Korea is also not a back-water exchange. In fact, the government has been proactive in trying to close the Korean-discount, following its neighbour market - Japan. In recent years, Korea has introduced regulatory reforms to protect minority shareholders, as well as initiating a Corporate Value Up program to fix Korean cost-of-equity - via improvement in capital allocation and encouraging entities to improve on their ROE. I won’t go into too much detail here but you can read more about this on Nate’s blog.
Today, I have two stocks to talk about, of which I included into my Korean basket.
One growthier name and one more net-net ish. Lets get right into it.
Global Tax Free (KOSDAQ: 204620)
Global Tax Free (GTF) is a leading tax refund service provider in South Korea, aiding international visitors the reclaim the Value-Added Tax (VAT) paid on retail goods. There are really only a few firms globally that do this, one of which includes the recently privatized Global Blue (GB) - which was taken out by Shift4 payments last year. I missed GB as a take out play, but if any of you can recall, Shift4 paid ~13x EBITDA - and management was upbeat about how they managed to snag GB on the cheap - it would be “worth twice as much in 2 years” (from the analyst call).
Business economics for a tax refund service is as follows:
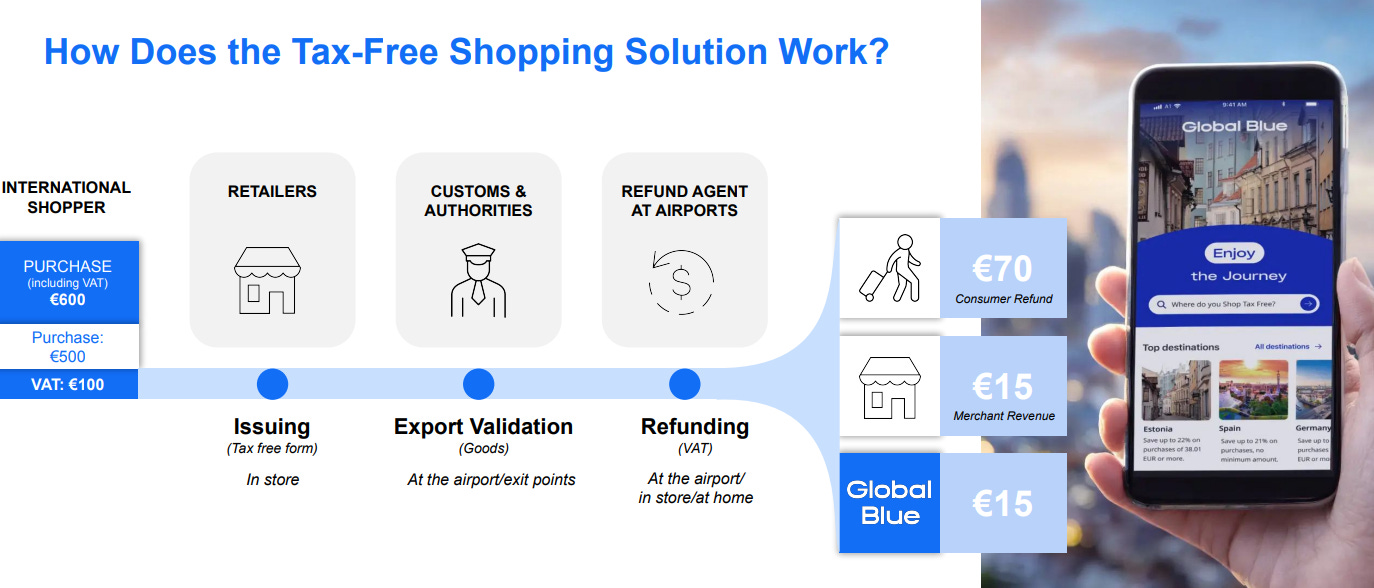
Accordingly, margins are high and growth is indexed to the growth in tourism within the designated geography.
Korea has become a top destination for tourists - note this recent article, and this article - as Korea has become a global cultural powerhouse - Hallyu - as they call it, anchoring the modern international zeitgeist. This rapid ascension in cultural relevance also meant tangential growth in medical surgeries, cosmetics and fashion-related.
Further helping GTF, in early 2024, the Korean government doubled the immediate refund limit per transaction to 1m KRW (US$700), expanded the total purchase limit to 5m KRW (US$3500), and slashed the minimum transaction threshold from 30,000 KRW to 15,000 KRW (US$10.60). This instantly qualified millions of everyday retail and beauty purchases for refunds, directly funneling massive volume into GTF’s exclusive merchant network which includes Olive Young and the top three domestic department store groups. This propelled growth in recent years, and given the relatively fixed cost structure, topline growth and margins have looked a little like this:
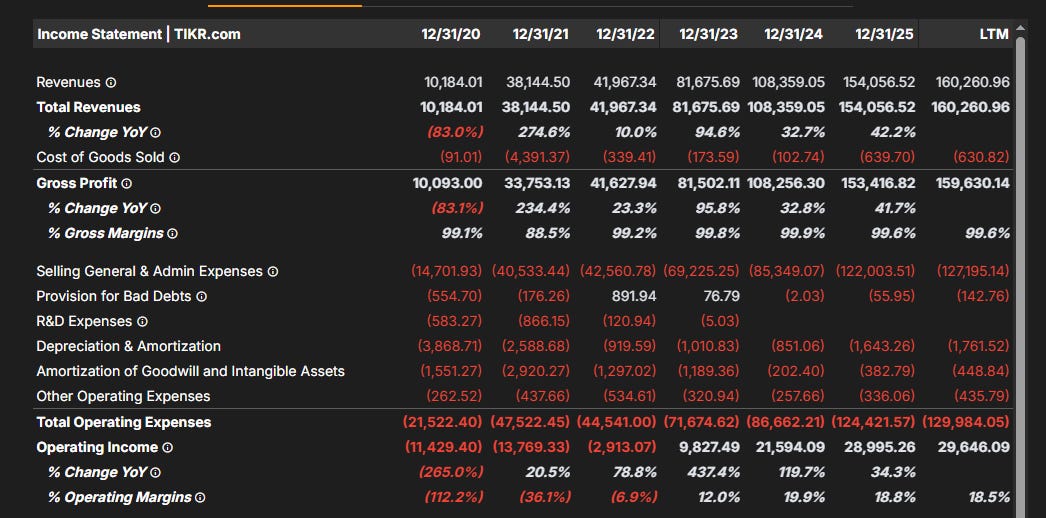
This is where we need to take a pause for a bit. In 2025, the government ended the medical cosmetic surgery VAT refund program, which was the largest driver of tourism and thus revenue (~20%). Whilst this initially knocked the stock off its boots a little, this has not made a dent at all in GTF’s operations.
In 1Q26, GTF domestic retail revenue grew ~22.6% YoY, in spite of the significant loss in cosmetic surgery related revenue i.e. ~50% organic growth in the remaining business YoY. Other geographies such as Japan and Singapore had continued to grow as well, though they only represent a small portion of revenue. This trend persisted even in June - see link here:
GTF announced on the 15th that sales in its domestic tax refund business division surpassed 14.7 billion won on a monthly basis for the first time in history in June. This figure represents a surge of approximately 30% compared to the same month last year and marks a new all-time high.
In particular, this achievement is noteworthy as it was accomplished by overcoming the revenue gap resulting from the expiration of the VAT refund for cosmetic surgery for foreigners. Excluding the expiration factor, the actual sales growth rate exceeded 50%, proving that the actual spending power of inbound tourists has significantly strengthened
..
"We are continuing to achieve record-breaking performance every quarter, driven by the steady increase in the influx of foreign tourists visiting Korea due to the spread of global K-culture and the government's K-tourism revitalization policies," said Oh Tae-seok, CEO of Global Tax Free. "As the second half of the year is the traditional peak season for foreign tourists visiting Korea, we can expect an additional rally in performance."
As per street estimates, lapping difficult comps, total revenue is still likely to grow by ~12% YoY for FY26, with operating margins at ~19% i.e. ~US$23m of EBIT. Again, this figure obscures the actual growth in the remaining business, which likely is our source of opportunity.
Additionally, as per the firm, 2027 is likely to see another significant jump in growth, as the difficult comps have been lapped and along with expansions into Japan (another major tourist destination). In November 2026, Japan will fully transition to a post-refund tax system, which as per GTF, opens up a new market worth ~US$200-400m annually. To facilitate this new market, GTF entered into a JV with Planet (the second largest tax refund operator in the world), whereby Planet invested ~US$6.5m for a ~49% stake in GTF’s Japanese subsidiary (alignment). As per the firm, Planet will bring its global luxury merchant network i.e. powerhouse brands like Gucci, Balenciaga, and Saint Laurent - alongside its DCC (Dynamic Currency Conversion) partners representing over 400,000 merchant locations. GTF, in turn, provides the local Japanese hardware, transaction clearing software, and physical refund terminal networks.
Japan is all icing, but even without that, where is GTF valued?
Tracking back a bit. GTF underwent a portfolio cleaning over the past year - acquiring full control of a cosmetic subsidiary Swanicoco as well as ramping up its stake in webtoon platform Finger Story, in the early part of the year. The firm then dumped both holdings in December, booking a small accounting loss but essentially streamlining its entire operations. Both entities were irrelevant and loss-making; post these divestments, GTF is now entirely VAT refund.
Over the past few years, GTF also cleaned up its capital structure, cleaning out its various convertible and exchangeable bonds which unfortunately expanded share count significantly by >30% since 2021.
Late last year, there was also a significant change in ownership with prior controlling shareholder (Moon Yang-keun) selling his stake to a consortium of investors (now called GTF Holdings) at a ~60% premium to the last trading price then (around KRW 8,650/share - still above the current trading price). Moreover, what rattled the market was that GTF then proceeded to announce a primary raise to the consortium at a 10% discount to the last trading price (more on that in the article link above). That was then scuttled the next day on grounds of violation of minorities. Note GTF Holdings proceeded to buy more shares in the open market early this year.
Sporting a market cap of around US$260-270m, US$90m of net cash and no debt, as well as ~US$25m of EBITDA for FY26, GTF trades at ~7x EBITDA. Over the LTM, GTF did ~US$30m of FCF so share are trading around 8-9x FCF.
In sum, GTF is a fast growing business that has been obscured by the lost in revenue due to the sunsetting of the cosmetic surgery VAT in Korea. As Korean tourism continues to grow, GTF should likely see continued growth as well as margin expansion (GB had an EBITDA margin of ~40%), not to mention expansion into other geographies.
Geumhwa Plant (KOSDAQ: 036190)
Geumhwa Plant (GP) builds, repairs and maintains heavy industrial facilities, servicing thermal, nuclear and renewal power plants in South Korea.
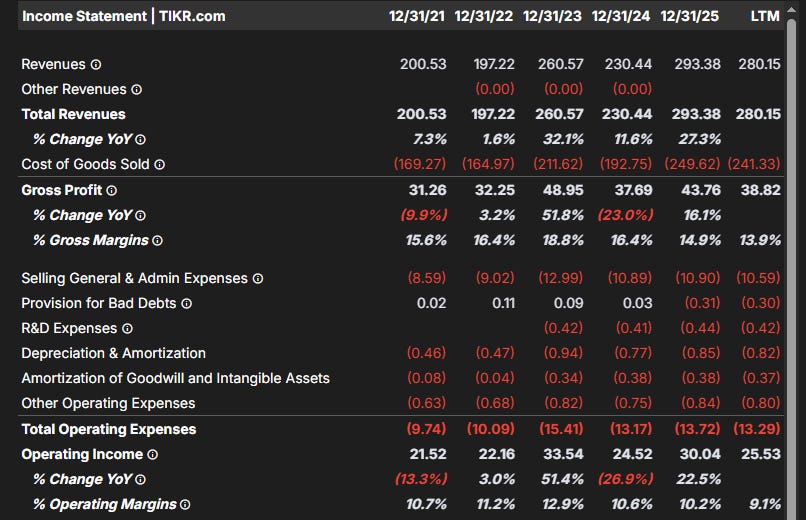
This is another nifty business that has grown decently over the past few years, albeit with an acqusition conducted in late 2022, whereby GP acquired Ecobit, a water treatment and wastewater business for a small token sum of <US$10m.
Still, revenue from its core operations had grown 12%, 0.5% and 28% in FY23, FY24 and FY25, respectively. The strong growth in FY25 was due to some active domestic nuclear and industrial projects - notably the Shin-Hanul #3 and #4 installations. Its water treatment business declined -0.6% in FY24 and snapped back to 15.5% growth in FY25.
The thesis here is quite simple.
GP has had a long history of providing industrial maintenance and repair services, as far as I know, has never had an unprofitable year. Capex needs are light and the firm is insulated from typical booms and busts in its end markets. Revenues are stable and recurring (by nature of power plant routine maintenance) and over 70% of its market cap is in net cash.
Going forward, GP is likely to put up 1) another strong year, and 2) there is a major shareholder that is incentivized to unlock value.
First and foremost, GP has reported strong backlog growth in recent years, backlog grew ~31-32% for both FY24 and FY25, respectively, with backlog-to-revenue coverage ratio increasing from ~7.3 months in FY23 to 10.1 months in FY25. Whilst a chunk of the current backlog will wash out in FY26 (this year will likely be a banger year) as they are short-term in nature, GP is in all the right end-markets.
One of the prevalent operational risks is the national phasing out of coal-fired plants (of which a major portion of GP’s cash flow came from); however, decommissioning takes time and GP has preemptively pivoted towards nuclear projects - winning two massive construction packages for South Korea's newest reactors, Shin-Hanul #3 and #4. The combined contracts signed over the past two years currently >US$72m in total and are recognized through 2031.
Apart from pivoting towards nuclear, GP’s water business has been important for semiconductor fabs. GP’s water business is essential for producing the Ultrapure Water required by high-tech semiconductor fabs and it has recently won a contract with Sk Hynix Yongin Cluster - AI Capx beneficiary-squared (?).
Second, Ancient Art LP is a longtime major shareholder, owning 13% of share capital has been an active shareholder at GP and a governance watch-bird - they have consistently pressed for a return of GP’s huge cash pile though to no avail so far. However, there was a minor change of tone recently. On the back of the Korean Value-Up mandate, GP had officially decided to raise dividends per share by 23%, distributing a cash dividend of 1,600 KRW/share this year, up from 1,300 KRW/share historically. This represents a ~5% dividend yield at the current share price.
GP currently trades at a ~US$130m mcap with ~US$100m of net cash which would imply an EV of US$30m against US$25-30m of EBIT over the past couple i.e. 1x EBIT. Recall, capex needs are deminimus. As most veteran speculators would know, there is value trap risk here unless GP puts up significant growth or returns a huge chunk of capital (which would be a significant change in corporate tone). But I’m comforted by the directional change in tone with the dividend raise and at worst, am paid decently to wait.
Disclose: own both in varying sizes
Love reading about Korean stocks. Also thanks for reminding me about the VAT refund changes in Japan, gonna have to budget in extra time at the airport this January. Cheers! :))
I looked at Geumhwa recently, and a few of its competitors. Two things stuck with me.
A lot of the maintenance contracts have no fixed end date. They just get pushed out six months at a time.
And the labour side. Under a 2021 industry agreement, when a plant changes maintenance contractor, the crew moves to the winner with their years of service. In February, KEPCO KPS (the state-owned one) agreed to directly hire its 593 subcontracted workers, and unions are now pushing for work done by private firms to go back to KPS.
That second one worries me more than the coal phase-out. Did you look at either?